How to Cancel a Klarna Payment Plan Without Hurting Your Credit (2026)
Quick answer: Cancelling a Klarna order will not touch your credit score by itself. Klarna does not report a routine cancellation or refund to Experian, Equifax, or TransUnion. What actually damages your credit is missing a payment by 30 days or more, since that is the point where Klarna starts furnishing the account to the bureaus. Contact the merchant first, let Klarna cancel the payment plan once the store confirms, and use the extend or pause options if the store is slow to respond.
A Klarna order sitting unpaid in your app is not automatically a credit problem. It becomes one only past a specific point, and most people cancel or fix the order long before that point arrives without realizing how much room they actually had.
When I checked Klarna’s own help center pages against the CFPB’s blog post on buy-now-pay-later credit reporting, the two lined up on one thing clearly: reporting behavior depends entirely on how late the payment gets, not on whether you cancel, dispute, or simply change your mind about a purchase.
Contents
- Does Cancelling a Klarna Order Actually Hurt Your Credit?
- How Do You Actually Cancel a Klarna Order?
- What If the Store Will Not Confirm the Cancellation?
- Extend, Pause, or Cancel: Which Option Fits Your Situation?
- What Happens If You Just Stop Paying Instead?
Does Cancelling a Klarna Order Actually Hurt Your Credit?
Cancelling a Klarna order does not hurt your credit score, because a cancellation and refund never gets furnished to a credit bureau in the first place. Klarna’s own customer service documentation treats cancellation as a merchant-side event: you contact the store, the store confirms, and Klarna unwinds the payment plan and refunds whatever you already paid.
Where the confusion usually comes from is Klarna’s Pay in 4 product feeling like a loan. It behaves like a loan in the sense that missed payments carry consequences, but it is not treated like a credit card for reporting purposes while you are current or working through a normal cancellation.
According to the Consumer Financial Protection Bureau’s blog on BNPL credit reporting, furnishing practices across BNPL lenders are inconsistent, and short-term Pay in 4 plans are the least likely product type to hit your file at all when handled on time.
How Do You Actually Cancel a Klarna Order?
You cancel through the merchant, not through Klarna directly, and that single fact trips up more people than any technical step in the process.
Open Klarna’s help flow for cancelling an order, contact the store that sold you the item, and follow that store’s own cancellation policy. Klarna’s role starts after the store confirms: it cancels the remaining payment schedule and refunds any amount you already paid back to your original payment method.
Refunds are not instant. Klarna states processing can take up to 14 days depending on your bank, and you can track exactly where the refund stands under Payments in the app the whole time.
Partial refunds work on a sliding scale. If the refunded amount is bigger than what you still owe, the extra gets credited back to your card. If it is smaller than your remaining balance, Klarna spreads the difference evenly across whatever payments are left on the plan.
What If the Store Will Not Confirm the Cancellation?
Slow or unresponsive merchants are the most common reason a Klarna cancellation stalls, and Klarna built a separate path for exactly this situation instead of leaving you stuck waiting on the store.
Inside the app, open the order, tap Report a problem, and select the option that matches what is going on — item never shipped, merchant unreachable, or a dispute over what you received. That flow pauses your payment plan while the issue gets sorted out, so nothing comes due and nothing goes delinquent while you wait.
This part trips a lot of people up. They assume the only options are pay on schedule or go delinquent, when pausing through a reported problem is sitting right there the whole time and stops the clock without touching your credit.
📌 Related reading: refund speed varies a lot by payment method — see how Chargeback vs. Refund Request: Which Gets Your Money Back Faster in 2026? breaks down the timeline when a merchant will not cooperate at all.
Extend, Pause, or Cancel: Which Option Fits Your Situation?
Three tools solve three different problems, and reaching for the wrong one is how a fixable situation turns into a missed payment.
| Option | Best for | Limit | Credit impact |
|---|---|---|---|
| Extend due date | You just need a couple more weeks to pay | Once per order, not available on Financing statements | None |
| Report a problem / pause | Item never arrived, merchant unresponsive, order disputed | Until the issue resolves | None while paused |
| Cancel through the merchant | You no longer want the item and the store agrees | Depends on store’s own return policy | None once confirmed |
✅ Quick gut-check: if the item is on its way and you just need more time, extend. If something is actually wrong with the order, report a problem instead of waiting silently. Only reach for a full cancellation once the merchant has actually agreed to unwind the sale.
What Happens If You Just Stop Paying Instead?
Ignoring a Klarna payment instead of using any of the three tools above eventually turns into exactly the credit event you were trying to avoid.
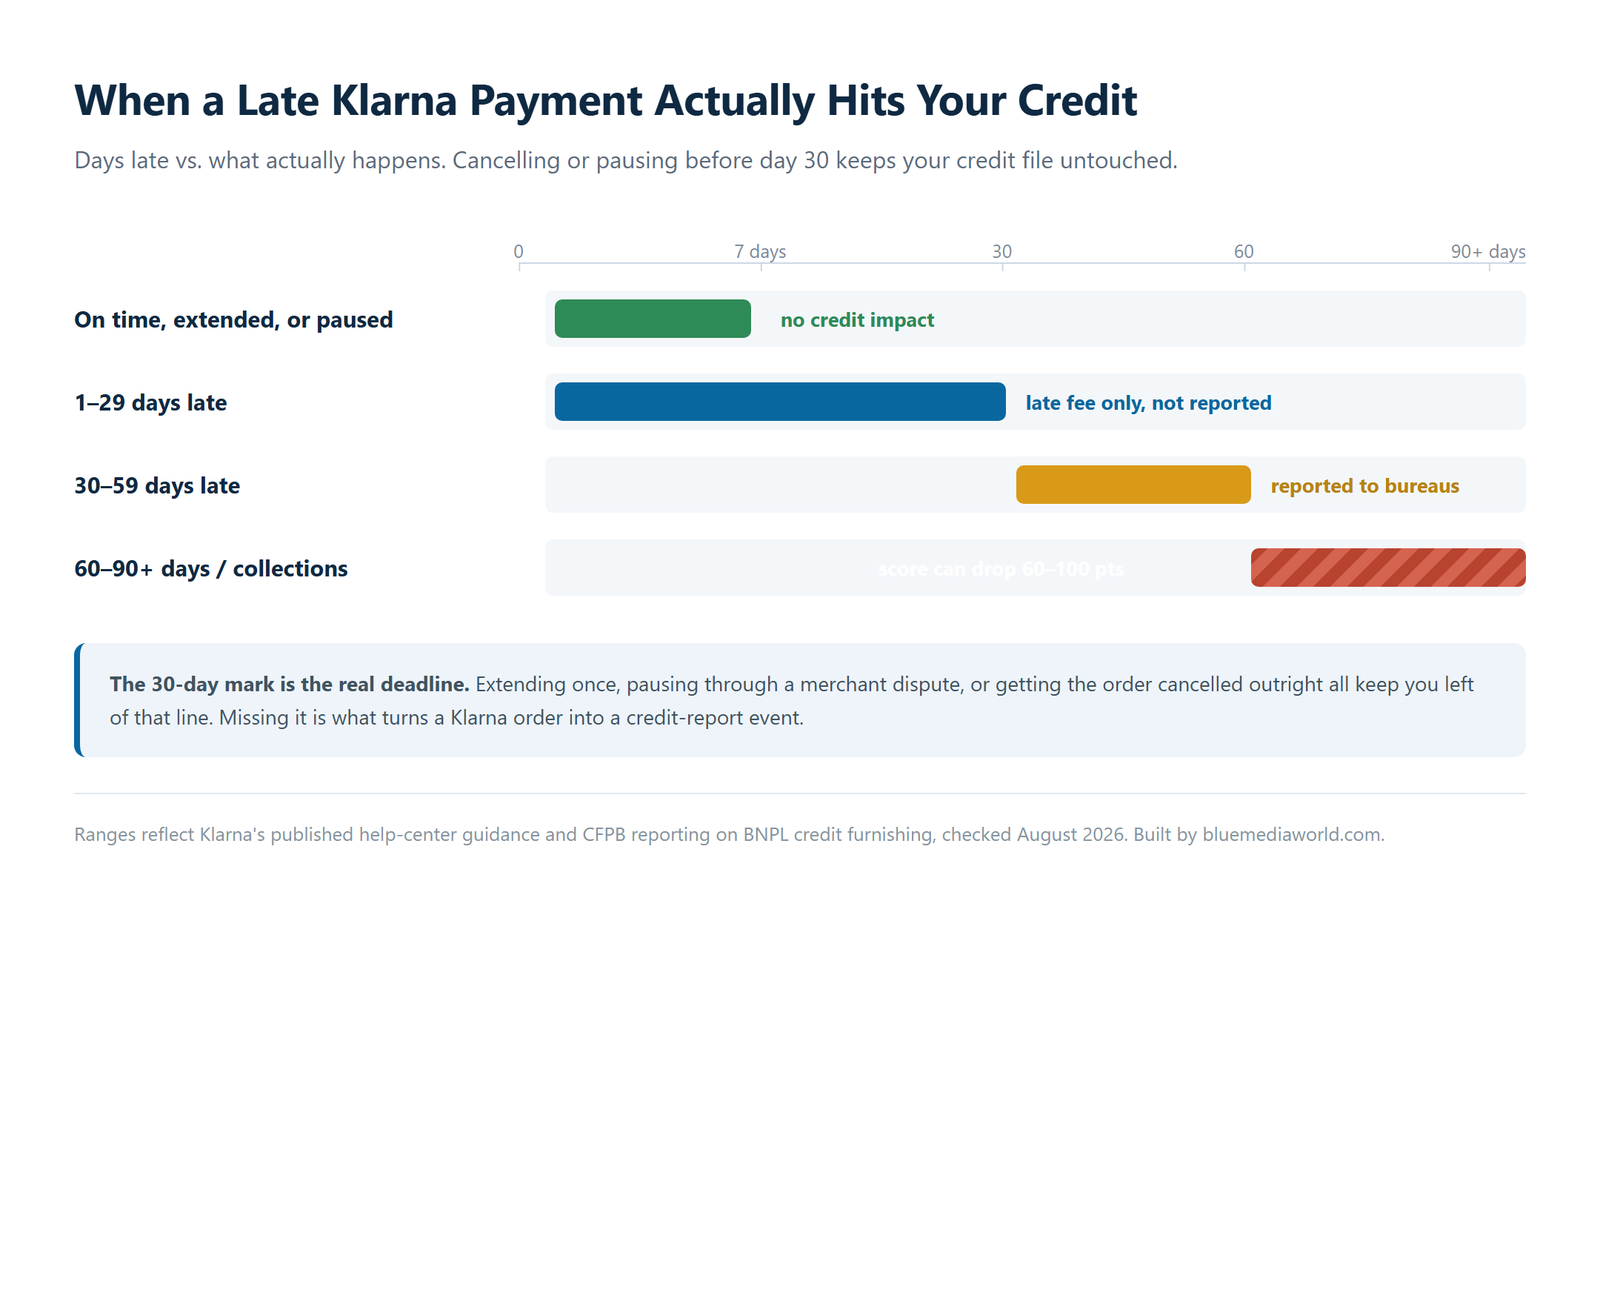
A single missed payment by a day or two does not get reported. In my experience checking through Klarna’s own late-payment guidance, the practical danger line sits at 30 days — that is the threshold where Klarna begins furnishing the account status to the bureaus, in line with what the CFPB describes as standard BNPL furnishing behavior once an account goes seriously delinquent.
Past that, the numbers get worse fast. Accounts that slide to 60 to 90 days unpaid and get sent to a collection agency can pull a credit score down by roughly 60 to 100 points, a range consistent across most consumer installment debt once it hits collections status.
You’ll probably notice state regulators are starting to pay closer attention here too. New York’s Department of Financial Services published proposed BNPL rules in 2026 that would require lenders to disclose upfront whether a plan gets reported to credit bureaus at all — a sign this space is getting less quietly inconsistent than it used to be.
Honestly, the fix is almost always cheaper than the consequence. Extending once costs nothing. A collections mark costs months of credit-score recovery.
Quick Checks Before You Cancel
- ✅ Contact the merchant first — Klarna cannot cancel a payment plan the store has not confirmed.
- ✅ Check Payments in the app for real-time refund status instead of guessing at the 14-day window.
- ✅ Use Report a problem the moment a merchant goes silent, not after a payment is already late.
- ✅ Remember the extend option only works once per order and never on Financing statements.
- ✅ If a payment plan already has a missed payment on it, check the exact days-late count before assuming the worst.
Where Does This Actually Go Wrong?
The most common mistake is contacting Klarna support first and waiting on them, when the store is who actually needs to confirm the cancellation. That misdirected wait is where most stalled cancellations come from.
The second mistake is assuming any lateness reports instantly. It does not — the 30-day mark is what matters, and panicking into a rushed decision before then usually is not necessary.
A quieter mistake: not reading whether an item was bought under a short Pay in 4 plan or a longer Financing statement. Financing plans cannot use the extend-due-date tool at all, so people try it, watch it fail, and assume the whole system is broken instead of switching to Report a problem.
FAQ
Does Klarna report Pay in 4 to credit bureaus if I pay on time?
No. On-time Pay in 4 payments are generally not furnished to Experian, Equifax, or TransUnion. Reporting only becomes likely once an account is seriously delinquent, typically past 30 days late.
Can I extend a Klarna due date more than once on the same order?
No. Klarna allows one due date extension per order, and the option is not available at all on Financing statement purchases, only on standard payment plans.
What should I do if a store will not respond to my cancellation request?
Use the Report a problem option inside the Klarna app instead of waiting. Selecting the issue that matches your situation pauses the payment plan until it is resolved, so nothing becomes late while you wait on the merchant.
Sources
- Klarna: How Do I Cancel My Order?
- Klarna: How Can I Extend My Due Date?
- Consumer Financial Protection Bureau: Buy Now, Pay Later and Credit Reporting
Fact-checked based on public sources as of August 20, 2026.