How to Read a Dividend ETF Fact Sheet Before You Buy
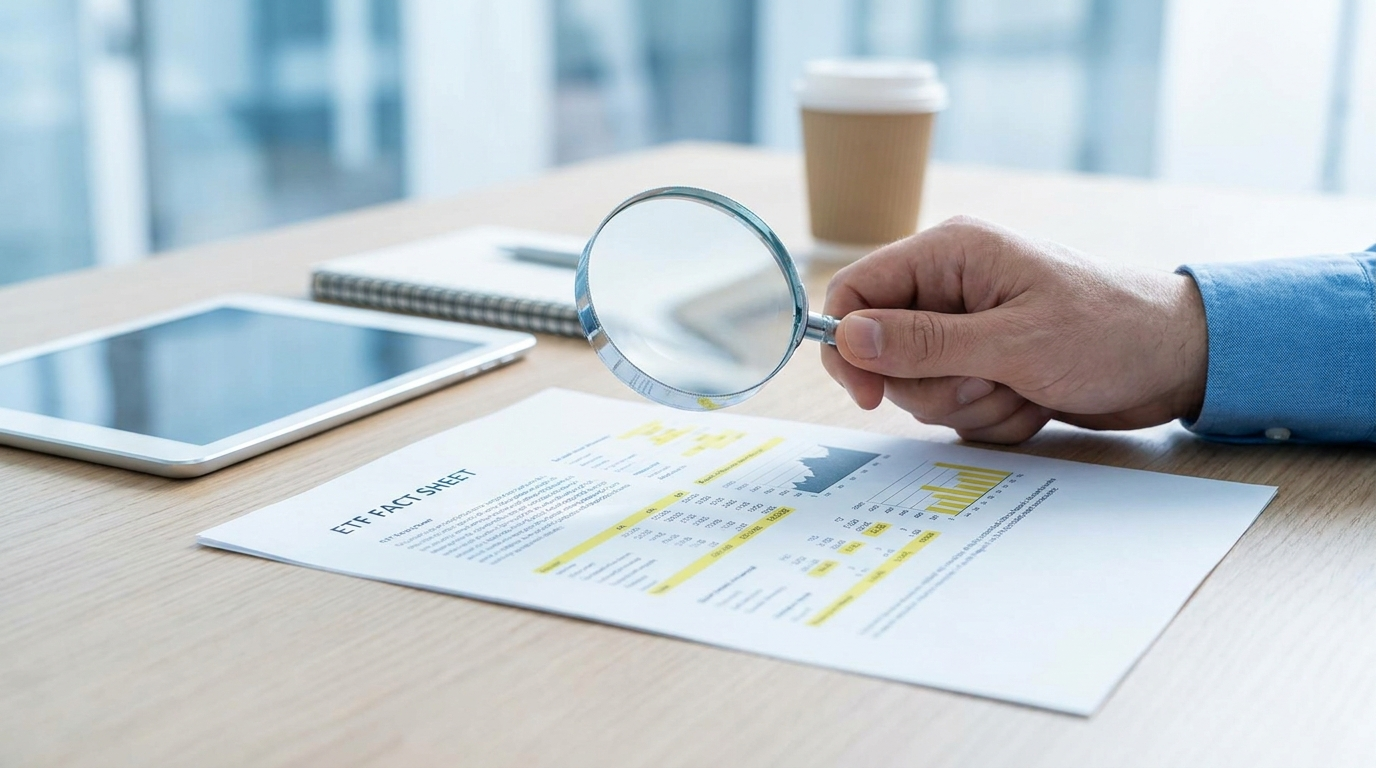
Here’s what I keep noticing. Most people crack open a dividend ETF fact sheet and go straight for the big yield number. The two or three figures that actually matter? Skimmed right past. I pulled a handful of popular dividend fund fact sheets one afternoon and lined them up side by side. The funds waving the highest advertised yield weren’t always the ones with the healthiest payout growth underneath. Not even close, some of them. So let me walk you through reading one properly. It takes about five minutes.
📌 Related reading: 2026 Best Dividend ETFs for Passive Income · How to Compare US and Korean Market Hours as a Foreign Investor
In This Guide
Steps
Step 1: Check the Expense Ratio First
Find the expense ratio near the top of the sheet. It’s the annual fee, shown as a percentage of what you’ve put in. Under 0.2% counts as low for a dividend ETF. Above 0.5%? You’d want a genuinely strong reason to justify it. Those fees compound against your returns every single year you hold the fund, so they matter more than that small number lets on.
Step 2: Look at the 30-Day SEC Yield, Not Just “Distribution Yield”
Fact sheets love to show you several yield figures at once. Only one is truly comparable. The SEC yield is the standardized one. The “distribution yield” can be puffed up by a single one-time payout. So compare SEC yields fund to fund, never distribution yields. This matters most when the marketing leads with the bigger, prettier number.
When I ran this comparison across several well-known dividend ETFs, the gap between the two figures sometimes cleared a full percentage point. That’s enough to flip which fund looks better on paper.
Step 3: Check the Top 10 Holdings and Sector Weighting
A dividend ETF can look beautifully diversified and still sit 40%+ in one sector. I’ve been caught out by this more than once. Scan the top 10 holdings. Glance at the sector breakdown pie chart. Do both before you assume you’re getting broad exposure. Financials and energy are the usual spots where dividend-focused funds quietly pile up.
Step 4: Review the 5-Year Dividend Growth Rate
This one tells you whether the payout has actually grown or just sat there. A high current yield with flat 5-year growth is a completely different animal from a lower yield that keeps climbing. The second often compounds better over time. Especially if you’re holding for years rather than months.
Step 5: Confirm the Distribution Frequency and Tax Classification
Check the payout schedule first. Monthly, quarterly, or annually? Then look at how the distributions are classified. Qualified dividends usually get taxed more favorably. Ordinary income does not. Hardly anyone reads this line. It still shapes your real after-tax return, sometimes by a noticeable chunk depending on your bracket.
A fact sheet shows the yield in large type and the expense ratio in small type. Put both in and see what the fee costs you in a year, and across a decade of holding.
The guide treats 0.2 percent as low for a dividend ETF
Educational arithmetic, not investment advice. It holds the balance flat to isolate the fee, so it understates the drag on an account that grows, and it ignores taxes on distributions. A distribution yield is trailing, not a promise of future income.
Tips
- ✅ Compare fact sheets from the same date. Funds refresh these quarterly, and mismatched dates will skew the whole comparison.
- ✅ Cross-check the expense ratio against the provider’s own website, since the PDF sometimes lags behind a rate change.
- ✅ Save the fact sheets for funds you’re actively weighing. It lets you track the changes quarter to quarter.
- ✅ Peek at the fund’s inception date. A short track record makes those 5-year growth figures thin or missing entirely.
- ✅ If a standard deviation or beta figure is listed, glance at it. It hints at how bumpy the fund has been against the wider market.
Warnings
⚠️ A high yield on its own is not a buy signal. It might come from genuine dividend growth. It might also come from a shrinking share price, which mechanically pushes the yield up while quietly destroying your capital. ⚠️ Past dividend growth guarantees nothing about the future; funds and companies do cut distributions during downturns. ⚠️ This article is for informational purposes only and is not investment advice.
References
Q&A
Where do I actually find a fund’s fact sheet?
Head to the fund provider’s site — Schwab, Vanguard, whoever runs it. Search the ticker plus “fact sheet.” It’s almost always a downloadable PDF, refreshed each quarter.
Is the fact sheet the same as the prospectus?
Nope. The fact sheet is the short summary. The prospectus is the full legal document, with far more detail on risks and fees.
Should I pick the fund with the highest SEC yield automatically?
I wouldn’t. A yield that towers over its peers can flag higher risk, heavy sector concentration, or a share price that’s sliding — not necessarily better income. Check the rest of the sheet before you commit.
Fact-checked based on public sources as of July 21, 2026.
Frequently Asked Questions
Is a fact sheet enough on its own, or should I read the prospectus too?
The fact sheet is a summary. The full prospectus and the most recent annual report contain fee details, risks, and holdings rules the sheet leaves out, so read both before taking a meaningful position. This is general information, not investment advice.
What if the fact sheet’s data is several months old?
Fact sheets are typically refreshed monthly or quarterly, so holdings and yields can be stale between updates. Confirm the “as of” date on the sheet and check the fund’s live page for current figures before you buy.
Does a low expense ratio guarantee better returns?
No. A low fee helps over time, but total return also depends on the underlying holdings, dividend sustainability, and market conditions. Do not treat the expense ratio as the only factor. General information, not advice.

Similar Posts
Apple Stock Drop vs Amazon Stock Surge: What the 2026 Earnings Reaction Really Means
TL;DR — Apple and Amazon reported record June-quarter results on the same night, July 30, 2026, and the market punished one and rewarded the other. Apple’s stock slid roughly 8% on weak forward guidance tied to memory and chip supply constraints. Quick answer: Apple and Amazon reported record June-quarter results on the same night, July…
SK Hynix Posted Record Profit and the Stock Still Fell 9.6%: What the Q2 2026 Miss Was Really About
TL;DR — SK hynix reported its most profitable quarter ever for Q2 2026 and the stock still closed down about 9.6%. Revenue of 79.32 trillion won and operating profit of 60.54 trillion won both landed under consensus, which sat near 84 trillion and 64 trillion. The shortfall was not weak demand. Quick answer: SK hynix…
S&P 500 vs KOSPI: 2026 Performance Comparison
TL;DR — Curious about Korean stocks? If so, you’ll probably line up KOSPI against the S&P 500 before anything else. Most foreign investors do. So here is how the two have actually stacked up. And what really drives the gap between them. Curious about Korean stocks? If so, you’ll probably line up KOSPI against the…
How to Compare US and Korean Market Hours as a Foreign Investor
TL;DR — Two markets. Two schedules. Here is the short version. The KRX runs about 9:00 AM-3:30 PM KST. The NYSE and NASDAQ run about 9:30 AM-4:00 PM ET. Under standard time, they never overlap. KOSPI closes hours before the US market even wakes up. Quick answer: Two markets. Two schedules. Here is the short…
SCHD vs JEPI vs Korean Dividend ETFs: Which Fits Your 2026 Plan?
TL;DR — You want dividend income in 2026 and you have two realistic routes: a US dividend ETF like SCHD or JEPI, or a won-denominated Korean fund like TIGER 배당성장. They are not interchangeable. You want dividend income in 2026 and you have two realistic routes: a US dividend ETF like SCHD or JEPI, or…
Why Your Limit Order Didn’t Fill: Common Causes and Fixes (2026)
TL;DR — Your limit order probably didn’t fill because the stock never actually traded through your price with enough size behind it. Seeing your number flash on a chart isn’t the same as trading at that number. Queue position matters, too — you can sit behind hundreds of shares at the identical price. Quick answer:…